Early Warning Signs Your Veteran Family Needs Immediate Financial Support
Changes in Daily Living and Self-Care Habits
You know that feeling when something’s not quite right, but you can’t put your finger on it? That’s often what veteran families experience in the early stages of financial hardship. The warning signs aren’t always loud or obvious. Sometimes they’re quiet, subtle shifts in behavior and routine that only loved ones close to the family will notice.
The tricky part is that these early indicators often get written off as temporary stress or a bad week. But when financial strain starts taking hold, it shows up in the most unexpected places first, not in a missed bill or overdue notice. It appears in how someone takes care of themselves, how they engage with their community, and how they manage the basic rhythms of daily life. Learning to spot these shifts early can make the difference between a manageable rough patch and a full-blown crisis that threatens housing, food security, and family stability.
Neglecting personal hygiene or home maintenance as stress indicators
This one hits different when you understand military culture. Veterans and their families are often trained to maintain standards, keep things in order, stay sharp. So when you notice a veteran or family member letting personal hygiene slide, skipping showers for days, wearing the same clothes repeatedly, or losing interest in grooming habits they normally prioritize, that’s a significant red flag.
The same applies to home maintenance. A normally tidy house starts accumulating dishes. Laundry piles up.
Yard work gets neglected. These aren’t character failures; they’re physical manifestations of emotional exhaustion and mental overload. When someone’s worried about making rent or affording groceries, the energy required for basic self-care and home upkeep simply disappears.
Financial stress is consuming mental bandwidth that would normally go toward these routine tasks.
Pay attention, too, to changes in appearance that suggest financial constraints. Worn-out clothing that hasn’t been replaced, untended injuries or health issues that go unaddressed because medical care feels too expensive right now, or visible weight changes. These patterns often emerge months before a family reaches a crisis point, giving you a window to intervene early with support like grants and assistance programs.
Withdrawal from social activities and community involvement
Veterans thrive on connection and community. Military culture builds identity around belonging to something larger than yourself. So when a veteran or military family member starts declining social invitations, skipping veteran community events they normally attend, or pulling back from faith communities or volunteer work, it’s worth investigating why.
Financial strain creates a special kind of shame that makes people isolate. They can’t afford to go out to dinner with friends. They can’t buy a coffee at a gathering.
They’re embarrassed about their situation. They fear judgment. Over time, these small avoidances become patterns.
A veteran who used to show up at every veterans’ organization meeting now makes excuses. A spouse who was active in their child’s school activities goes silent. A family member stops attending religious services because there’s no money for gas or because wearing older clothes feels humiliating.
This isolation actually accelerates financial problems because it cuts off access to support networks, information about resources, and the psychological benefit of community connection. When you notice someone withdrawing from activities that matter to them, that’s an opportunity to check in and understand whether financial constraints are driving the behavior. Programs focused on building financial stability can help restore dignity and reconnection.
Increased reliance on others for basic household tasks
Watch for patterns where a veteran or family member suddenly needs help with things they used to handle independently. This might look like repeatedly asking family members to provide transportation because a car payment is missed. Or requesting help paying for groceries. Or borrowing money for utilities. Or asking others to help with childcare because they’ve lost employment.
The escalating dependence is the real indicator here. One or two requests might be routine. But when you see a pattern of increasing reliance on others for basic needs, that’s financial strain manifesting.
Veterans especially struggle with this because self-reliance is deeply embedded in military identity. Asking for help feels like failure. But the requests keep coming because the underlying financial problem isn’t being addressed.
Understanding that timely veteran grants can help families access structured support before they’re forced into constant, informal dependence on friends and family.
Signs of substance use as a coping mechanism
Financial stress is a known trigger for increased substance use among veterans. When someone’s drowning in worry about bills, facing potential eviction, or unable to provide for their family, self-medication becomes tempting. Increased alcohol consumption, new reliance on medications beyond prescribed amounts, or emergence of drug use patterns are serious warning signs that financial pressure is creating crisis-level stress.
This doesn’t always look dramatic. It might be more drinking than usual at social gatherings. Increased prescription medication use. Spending money they don’t have on substances while bills go unpaid. Family members might notice empty bottles, changes in behavior linked to substance use, or defensive responses when the topic is raised.
Early intervention through crisis assistance and financial support can interrupt this pattern before addiction compounds existing problems. Resources available through organizations supporting veteran families can provide immediate emergency help alongside pathways to comprehensive recovery support.
Behavioral and Emotional Warning Signals
Persistent anxiety or depression related to financial matters
When a veteran starts showing signs of persistent anxiety or depression tied directly to money worries, it’s often a red flag that financial stress has crossed from manageable to critical. This isn’t just feeling stressed about bills. This is the kind of worry that keeps them awake at night, that shows up in their body language when money comes up in conversation, that makes them snap at loved ones over small expenses.
Many veterans experience service-related trauma that makes financial instability hit differently. The loss of control, the uncertainty about what comes next, the fear of letting their family down—these triggers can spiral quickly into serious mental health concerns. A veteran who previously handled setbacks with resilience might suddenly feel overwhelmed by routine financial pressure. They might withdraw from activities they used to enjoy or express hopelessness about their situation improving.
The connection runs both ways too. Untreated anxiety and depression can actually make financial decisions worse. When someone’s in crisis mode, they’re less likely to research va benefits 2025 or explore assistance programs that could genuinely help. This is why recognizing this warning sign early matters. Getting intervention during those first months of financial strain can prevent the mental health piece from becoming as serious as the money piece.
Increased irritability or mood swings when discussing money
Pay attention when conversations about finances trigger sudden anger, frustration, or defensive reactions. A veteran who normally keeps their cool might snap unexpectedly when you mention a past-due utility bill. Or they oscillate—one moment they’re fine, the next they’re in a full panic about rent being due in two weeks.
This isn’t character flaw territory. This is stress response. The brain in survival mode isn’t great at regulating emotions. When financial pressure piles up, veterans often feel like they’re failing in their fundamental role as a provider or protector for their family. That shame combined with the genuine fear of housing instability or inadequate food creates a volatile emotional environment.
The irritability might show up as sharp responses to family members, reluctance to talk about finances at all, or even anger directed at themselves. Some veterans mask it with humor or deflection, changing the subject whenever money comes up. Others become hypervigilant about spending, criticizing every household expense as wasteful.
These behavioral shifts are communication. Your veteran is telling you (even if they’re not saying it with words) that the financial pressure is getting unbearable.
Avoidance of opening bills or discussing finances with family
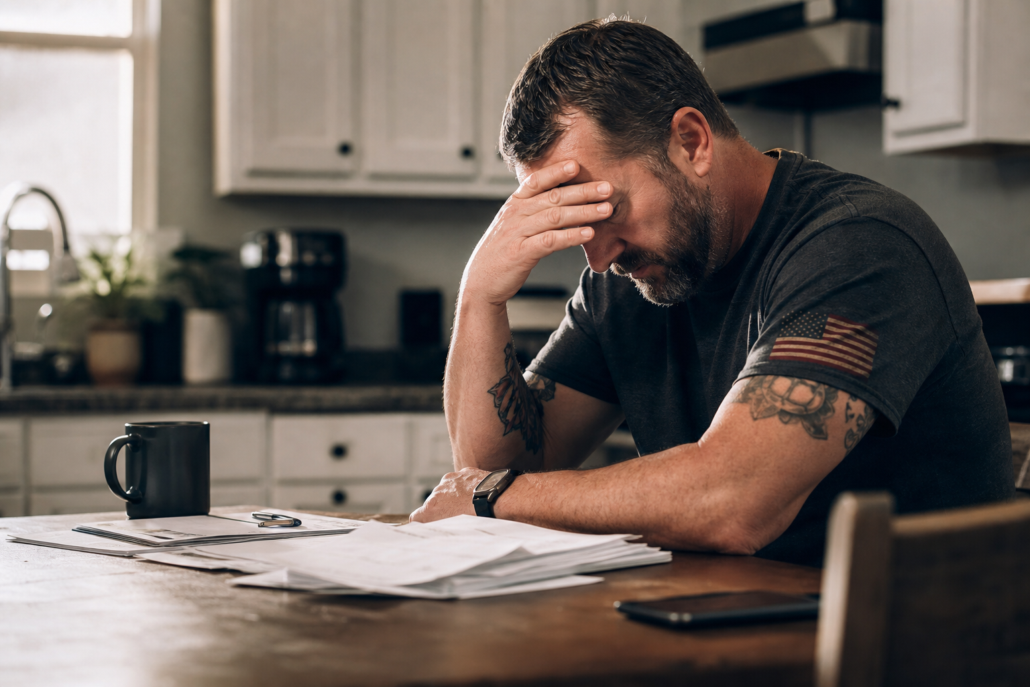
When bills start piling up unopened on the kitchen counter, when a veteran refuses to talk about the budget, when they actively prevent their spouse from looking at bank statements—these avoidance patterns matter. A lot.
Avoidance typically signals shame, fear, or both. The veteran knows there’s a problem but feels so powerless or embarrassed that they can’t face it directly. Opening that electric bill becomes a trigger.
Having “the money talk” with their partner feels impossible. The thought process often goes something like: if I don’t acknowledge it, maybe it will go away. Spoiler alert: it doesn’t work, and the problem compounds.
This avoidance also means critical deadlines slip. Enrollment windows close. Payment plans don’t get set up. Assistance applications don’t get submitted. A temporary cash flow issue becomes a crisis because the veteran couldn’t face making one phone call to their creditor or benefits office. If your veteran is displaying serious avoidance around finances, they likely need external support to break the cycle. That might mean help from an organization focused on injured veteran’s family or simply a trusted family member stepping in to handle initial conversations.
Signs of isolation or reluctance to seek help
Isolation is often the biggest warning sign of all. A veteran who stops reaching out to friends, who declines social invitations, who becomes secretive about their situation—they’re pulling away because of shame. The belief that asking for help is weakness runs deep in military culture, and financial hardship can intensify that feeling ten-fold.
Many veterans won’t mention they’re struggling until things are dire. They’ll keep quiet about missed mortgage payments or food insecurity because admitting it feels like admitting defeat. Pride, combined with financial fear, creates a perfect storm of isolation. This is dangerous because isolation removes the support network that could actually help them access resources.
Watch for reluctance to talk to family members, resistance to connecting with other veterans, or flat-out refusal to explore assistance programs. A wounded veteran charity exists precisely for this reason: to bridge the gap when veterans won’t help themselves. Sometimes the intervention needs to come from a spouse, adult child, or trusted friend gently insisting that reaching out is strength, not weakness. Early financial support prevents isolation from deepening into something much more serious.
Missed Deadlines and Enrollment Opportunities
Overlooking critical benefit application deadlines
Here’s something that catches many veteran families off guard: benefit deadlines don’t announce themselves loudly. They arrive quietly in the mail, get buried in email inboxes, or slip past while someone’s managing a crisis. Missing a single deadline can mean waiting months (or longer) for critical income, healthcare coverage, or housing assistance that your family desperately needs.
VA benefits, disability compensation increases, survivor benefit plan enrollments, and dependent education benefits all have hard cutoff dates. If you miss the window, reapplying often means starting from scratch. Some deadlines are only 30 or 60 days long. When a veteran family is already stretched thin juggling employment, medical appointments, and caregiving responsibilities, those narrow windows become invisible.
The warning sign here isn’t always obvious. It’s the unanswered mail stacking up. It’s someone mentioning, “Yeah, I got something about that but didn’t look at it yet.” It’s the calendar not being updated or shared across the household.
If you’re noticing that letters from the VA, state veteran agencies, or benefit administrators aren’t being opened promptly, that’s a red flag. Your family might be one missed deadline away from losing access to assistance programs or delayed benefits that could stabilize your situation.
Failure to complete veteran benefits enrollment requirements
Enrollment deadlines are different from application deadlines, and they’re sneaky. Many veterans qualify for benefits but never actually complete the enrollment paperwork. Forms sit unfinished. Required documents get lost. Phone calls to schedule appointments get postponed. And meanwhile, the veteran isn’t receiving support they’re already entitled to.
This happens for real reasons. The VA paperwork is complex (even when it shouldn’t be). Some veterans experience anxiety about navigating bureaucracy, especially if previous claims were denied.
Others are dealing with service-connected conditions that make sustained focus difficult. A spouse or family member might handle finances, but if there’s unclear communication about what’s pending, nothing gets done.
Watch for these specific signs: a veteran says they’ve applied for something but “haven’t heard back,” yet months have passed. They mention needing to provide documents but haven’t gathered them. They talk about qualifying for a benefit but say “it’s too complicated to set up.” If your family is managing financial stability, incomplete enrollments mean money is sitting on the table unclaimed. Pushing through that enrollment friction right now could unlock assistance your family qualifies for immediately.
Delayed medical appointment scheduling or missed preventive care
When finances tighten, veteran families often delay non-emergency medical appointments. Preventive care gets pushed back. Medication refills are timed differently. Specialist visits are scheduled months out instead of weeks out. This isn’t necessarily about not caring for health. It’s about prioritization when resources are limited.
The problem is that preventive care delays create emergency situations. A skipped annual checkup means a health condition progresses undetected. A delayed dental appointment becomes an infection.
A postponed mental health session leaves someone struggling without support. Veterans already understand mission-critical priorities, but when financial stress enters the picture, health calendars become flexible.
If you’re noticing that a veteran in your household is saying no to appointments or rescheduling them repeatedly, that’s worth taking seriously. Listen for the language: “I’ll reschedule for later,” “It’s probably fine, I’ll wait,” or “We don’t have the gas money this week to drive to the appointment.” These aren’t just scheduling delays. They’re symptoms that financial pressure is affecting health decision-making. Addressing immediate financial hardship through programs that provide bridges can help restore healthcare as a priority.
Non-response to financial assistance program notifications
Organizations like Operation Family Fund regularly reach out to veterans and military families about assistance opportunities. Notices arrive about emergency grants, housing support, caregiver aid, and other programs designed to prevent financial crisis. Yet some veteran families don’t respond. Sometimes it’s oversight. Sometimes it’s distrust. Sometimes it’s shame about needing help.
When someone doesn’t open letters about financial assistance, or doesn’t follow up after learning about programs, it often signals they’re struggling emotionally with their situation. Financial hardship carries real stigma, particularly in military culture where self-reliance is valued. A veteran might recognize they need help but feel uncomfortable accessing it.
The warning sign is avoidance. Nobody mentions the program notices. If you ask directly, there’s hesitation before responding.
Or someone admits they got information but “haven’t gotten around to it.” In crisis moments, veteran families need immediate, rapid intervention. Delays in responding to assistance notifications can mean your family misses windows for emergency support. If you’re recognizing these patterns around how your household handles notifications about programs or benefits, that’s your signal to take action this week, not next month.
Visible Financial Strain and Housing Instability
Difficulty paying utilities, rent, or mortgage consistently
When a veteran family starts missing utility payments or paying them late, it’s not usually a one-time slip-up. Late fees pile on. Service disconnection notices arrive. The lights flicker off for a few hours before another payment scramble happens. This pattern signals something deeper than a bad month.
Rent and mortgage payments tell an even clearer story. Veterans who’ve always paid on time suddenly start calling landlords or lenders asking for extensions. They’re making partial payments instead of full ones. They’re borrowing from family to cover the gap. These aren’t decisions made lightly, especially for someone with military discipline and a deep sense of obligation.
The immediate financial stress hits hard when housing costs consume more than 30 percent of household income, which is exactly where many veteran families find themselves after service-related injuries or job transitions. What makes this particularly dangerous is how quickly it escalates. One missed payment becomes a warning. Two become a pattern. Three become grounds for formal action.
Watch for conversations shifting toward housing anxiety. A veteran who’s always been straightforward about money might start avoiding the topic entirely or become defensive when asked about bills. This emotional shift often precedes the financial crisis by weeks.
Receiving eviction notices or foreclosure warnings
An eviction notice or foreclosure warning is beyond an early warning sign, it’s a crisis indicator that demands immediate action. If you’re seeing formal legal documents arrive at your veteran family member’s home, the window for preventive support has largely closed. Now it’s about crisis intervention and rapid placement of emergency resources.
The timeline matters here. Once an eviction notice is filed, most states give tenants 30 to 60 days before actual removal proceedings begin. Foreclosure timelines stretch longer, typically 90 to 120 days, but the psychological weight hits immediately. A veteran receiving these documents experiences real panic, even if they’re not saying it out loud.
What’s critical to understand is that homelessness among veterans isn’t always preceded by months of obvious warning signs. Sometimes it happens fast, especially when a service-related disability flares up, triggering unemployment, which triggers inability to pay housing costs. Housing instability cascades quickly into homelessness without immediate intervention and comprehensive support systems in place.
If you know a veteran family facing eviction or foreclosure, connecting them with organizations focused on veteran housing assistance and emergency financial aid isn’t optional. These situations require rapid response. Many communities now have veteran-specific housing programs with expedited approval processes because stakeholders understand the urgency.
Choosing between essential expenses like food and medications
This is where financial strain becomes a health crisis. Veterans who mention skipping doses of medications to make prescriptions last longer. Families rationing food by the end of the month. A spouse working overtime so someone can afford both groceries and the service dog’s veterinary care for the veteran’s PTSD.
These aren’t abstract hardships. They’re happening in military families across the country right now. A veteran managing a traumatic brain injury on medications that cost hundreds monthly faces a genuine choice: pay for the prescription or pay for utilities. There’s no good answer, and the stress of making that decision compounds the underlying condition.
Food insecurity among veteran families is documented and measurable. When a veteran starts mentioning that “groceries are getting tight” or a spouse mentions they’re “not as hungry as usual” to leave more food for the kids, you’re witnessing real deprivation. This accelerates both physical and mental health decline.
The connection between financial stress and medication compliance is direct and dangerous. Missing doses, skipping refills, or stretching prescriptions longer than prescribed undermines treatment effectiveness and creates new crises down the line. It’s why timely veteran grants that spin out of control.
Increasing debt and creditor contact attempts
Creditor calls increase when debt goes unpaid. That’s mechanical and predictable. What matters more is how the veteran or their family responds to these calls. Avoiding them entirely. Not opening mail from creditors. Becoming angry or withdrawn when the topic surfaces.
Credit card debt, medical debt, and personal loans compound quickly when a veteran family experiences employment disruption or unexpected medical costs. One missed payment becomes two. Interest accrues. Late fees stack. Collection agencies enter the picture. The psychological toll of constant creditor contact creates anxiety that mimics or worsens service-related conditions.
Medical debt specifically plagues veteran families because service-related injuries mean ongoing treatment costs that VA benefits don’t always fully cover. Out-of-pocket expenses for specialists, equipment, and therapies accumulate fast. Creditors don’t care about disability service connection. They want payment.
When you notice increasing debt, combined with other warning signs already mentioned, the veteran family needs structured financial support. This isn’t shame territory. It’s intervention territory. Many creditors will negotiate payment plans or settlements, especially when a nonprofit advocate representing the veteran family steps in with documented hardship and a real assistance plan.
Employment and Income Disruptions
Job loss or sudden reduction in work hours
One of the most immediate red flags that a veteran family is heading toward financial crisis is an abrupt change in employment status. Whether it’s a layoff, a company closure, or sudden cuts to hours, the income shock hits fast and often catches families unprepared. Many veteran households operate on tight budgets where every paycheck is already allocated before it arrives, leaving little room for adjustment.
Watch for signs like your spouse or family member mentioning unexpected schedule changes, being called into meetings about “restructuring,” or mentions of reduced shifts at work. These conversations might seem casual in the moment, but they’re often the first warning that income is about to drop. The psychological impact matters too. Job loss carries real shame and stress for many veterans, so they may downplay how serious the situation is or delay telling you until the problem has escalated.
A reduction in work hours is particularly tricky because it’s not always visible as a crisis. Someone can still be employed but earning 30-40% less if their hours got cut. Over a few months, this compounds into missed utility payments, delayed rent, and the kind of cascading financial pressure that families don’t recover from without intervention. If your family member’s paycheck is suddenly smaller, that’s a sign to have a direct conversation about whether temporary financial assistance could prevent larger problems down the road.
Struggles transitioning to civilian employment after service
The civilian job market operates completely differently from military service, and many veterans struggle to translate their training, discipline, and skills into language that civilian employers understand. This transition challenge often means veterans either take lower-paying positions than they’re qualified for or experience longer stretches of unemployment while searching for appropriate work.
The employment gap matters. Months of searching for the right fit can deplete savings quickly. Some veterans face difficulty with interview skills, resume writing, or explaining military experience in civilian terms.
Others encounter discrimination or unconscious bias. Some struggle with the unstructured nature of civilian work after years of clear chains of command and defined objectives. These barriers are real, and they lead to underemployment, which means steady paychecks that still don’t cover family expenses.
If you notice your family member has been job searching for longer than expected, or if they’ve accepted positions that pay noticeably less than their previous work, this is a warning sign worth addressing. Career coaching and employment support programs can help bridge this gap, but they take time. Financial assistance during the transition period is often the difference between stability and crisis. Consider whether grants, aid, could support your family member’s employment journey.
Inability to maintain employment due to service-connected disabilities
Some veterans face a harder reality. Service-connected disabilities, whether physical injuries, chronic pain, traumatic brain injury, or PTSD, make it difficult or impossible to maintain full-time employment. This isn’t laziness or lack of motivation. It’s a medical reality that affects earning capacity directly.
A veteran might be able to work part-time but struggle with the structure and stress of full-time jobs. They may have good days and bad days, making consistent attendance challenging. VA disability benefits provide some income, but those payments rarely match what full-time employment would provide. The gap between what disability benefits cover and what living expenses actually cost is where many veteran families fall into financial hardship.
You might notice your family member expressing frustration about physical limitations, frequent absences from work due to medical appointments or flare-ups, or conversations about reducing hours to manage their condition. These are all signs that employment income is about to become unstable. Paired with the emotional toll of managing a service-connected disability, this situation creates both immediate financial pressure and the stress we covered in previous sections. Understanding that this is a legitimate barrier to income, not a personal failing, is crucial for how families approach solutions together.
Inadequate income to cover family living expenses
Even employed veterans sometimes face a situation where their paychecks simply don’t cover what the family needs to survive. Rent, utilities, food, transportation, childcare, medications, and insurance add up fast. In high-cost areas, a veteran earning $15 or $16 per hour might be working full-time but still falling short every single month.
This chronic income-expense mismatch is insidious because it doesn’t show up as obvious job loss. Your family member is employed, showing up to work, doing their part. But the math doesn’t work. They’re slowly falling further behind each month, accruing small debts that balloon into larger problems. Financial stress points often reveal this underlying issue, especially when unexpected expenses hit and there’s no buffer to absorb them.
If your family member is bringing home a paycheck but you’re still seeing missed bills, growing credit card balances, or conversations about choosing between necessities, this is the pattern to watch. Income adequacy matters as much as employment status itself. This is where rapid, temporary assistance can stabilize the situation while longer-term solutions like better employment or additional benefits take time to develop.
Taking Action: Next Steps for Family Members
Opening conversations about financial concerns with compassion
Recognizing the warning signs is only half the battle. The harder part, frankly, is actually bringing up money with someone you care about. Veterans often feel shame around financial struggles (especially after service), so approaching the conversation requires real sensitivity.
Start by creating a safe, private space. Don’t ambush your veteran at a family dinner or when they’re stressed about work. Instead, pick a calm moment and frame the conversation around care, not judgment.
You might say something like: “I’ve noticed you seem really stressed lately, and I care about you. I want to understand what’s going on so I can help.” Notice you’re not accusing or assuming. You’re opening a door.
Listen more than you talk. Veterans have spent years taking orders and pushing emotions down. When they finally open up about financial pressure, your job is to listen without trying to fix everything immediately.
Ask clarifying questions. What bills are piling up? Did a job loss trigger this?
Is a family member’s medical crisis draining savings? The root matters because the solution depends on understanding the actual problem.
Avoid shame-based language. Don’t say things like “How did you let it get this bad?” or “Why didn’t you tell us sooner?” These statements shut down communication faster than anything. Instead, normalize struggle: “Financial pressure happens to a lot of people, especially after service. We’re going to figure this out together.”
Researching veteran-specific financial assistance programs
Once you’ve opened that conversation, your next move is understanding what resources actually exist. Generic financial aid programs sometimes won’t work for veterans because they don’t account for military-specific circumstances like delayed VA benefits, service-connected disabilities, or deployment-related employment gaps.
Start by learning what programs are available in your veteran’s situation. VA disability compensation, survivor benefits, education benefits, and home loan programs each have different eligibility rules and timelines. If your veteran hasn’t yet filed for benefits they qualify for, that’s often the fastest path to relief. But the VA process moves slowly, and bills don’t wait for paperwork to process.
That’s where emergency assistance comes in. Organizations focused on veteran families understand the urgent gaps between crisis and benefit approval. Resources like a wounded veteran charity can provide rapid grants for immediate needs while longer-term benefits work through the system. Timely emergency support keeps families stable during those critical weeks or months when standard resources aren’t yet available.
Look for programs offering not just one-time grants but comprehensive support. The best assistance includes employment coaching, financial counseling, and ongoing case management. These wraparound services address the underlying financial stress, not just the immediate crisis.
Connecting with local veteran service organizations and resources
Every region has veteran service organizations ready to help. These aren’t distant national bureaucracies. These are local groups with staff who understand your community’s specific challenges and resources. They know which landlords work with veterans facing housing instability, which employers actively hire transitioning military personnel, and which programs have short waiting lists versus lengthy backlogs.
Start by contacting your local VA regional office’s veteran service officer. They’re free, they know the system intimately, and they’re specifically trained to connect families with available resources. County veteran service officers do the same work at a more local level. Many have direct relationships with emergency assistance programs, housing nonprofits, and employment partners.
Don’t overlook nonprofit organizations focused on specific veteran populations. If your veteran served in a particular branch, there are often service organizations dedicated to that community. The same applies if they’re a caregiver, a surviving family member, or a veteran facing homelessness. Specialized organizations understand unique needs and often have targeted funding.
Your state may also offer veteran-specific financial assistance or emergency programs. Some states have rapid-response funds for housing emergencies or utility crises. Others provide employment grants or small business startup capital. A quick search for “veteran financial assistance [your state]” often uncovers programs most people don’t know exist.
Assisting with benefit applications and documentation
Here’s where many families stumble: applications are exhausting. VA forms require military records, medical documentation, and detailed financial disclosure. The paperwork alone can derail someone already overwhelmed by financial stress. Your role as a family member often becomes paperwork navigator.
Gather what your veteran needs before starting. Discharge papers, medical records, proof of income, proof of residency, and any previous correspondence with the VA. Organize these in one folder, physically or digitally. This simple step saves weeks of frustration.
If applications feel too complex, your veteran service officer can help complete them. So can accredited representatives from nonprofit organizations. You don’t have to do this alone, and honestly, trained advocates often get faster results than family members working blind.
When your veteran is facing immediate financial hardship while waiting for benefit decisions or application approvals, emergency grants bridge that gap. Organizations that understand veteran circumstances can process rapid support within days rather than months, keeping families housed, fed, and stable while longer processes work. The goal is simple: help your veteran family member move from crisis to stability, knowing that reliable support exists at every step.
Reach out to your local veteran community, ask the hard questions, and remember that seeking help isn’t weakness. It’s exactly what your veteran would do for someone else in uniform.
Related Posts
- Operation Family Fund Kicks Off
- First Donation to Operation Family Fund Comes from Eleven Year-Old
- Operation Family Fund to Exhibit at Upcoming 2007 Gold Coast Navy Show
- Operation Family Fund Raises Over One Million Dollars in Donations
- Santa Barbara Harley Davidson & Dr. Laura Host Motorcycle Show and Benefit for Operation Family Fund
- Santa Barbara Couple Donates $5,000 to Operation Family Fund in Support of Our Troops

Leave a Reply
Want to join the discussion?Feel free to contribute!